Redefining Retirement: 3 New Lifestyle Models for Americans in 2026
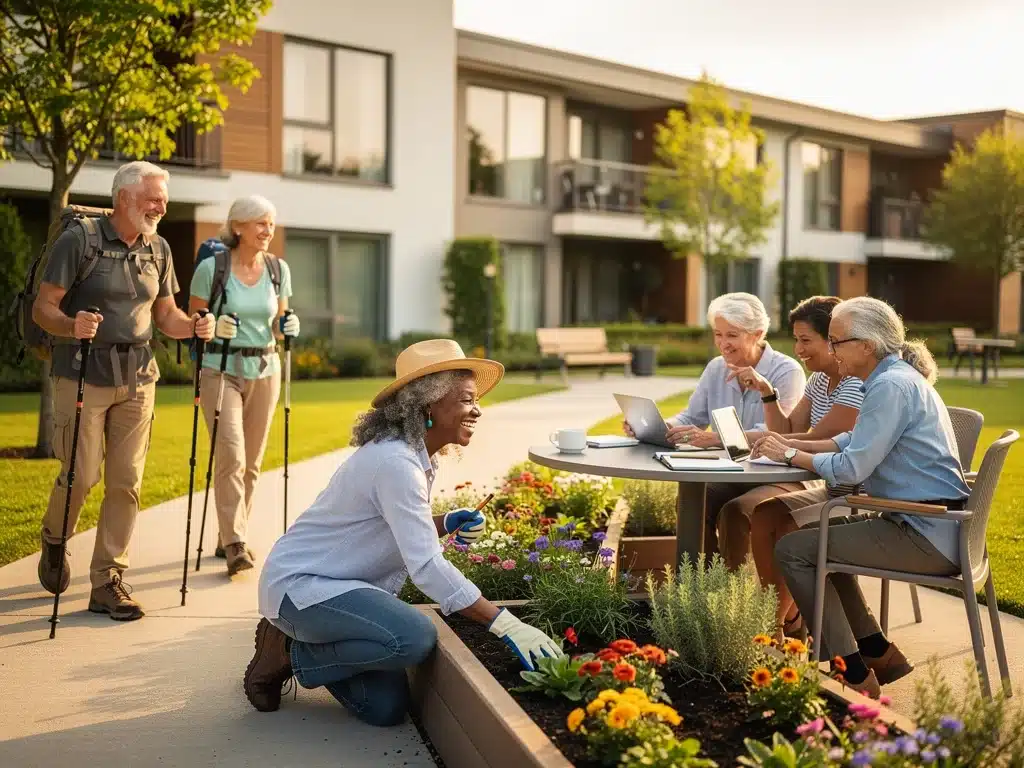
In 2026, Redefining Retirement in the United States increasingly means considering flexible work, purpose-driven activity and shared living arrangements alongside traditional full retirement.
These three lifestyle frameworks can help Americans think more broadly about income, housing, purpose and long-term financial resilience.
Redefining Retirement in 2026 does not mean that traditional retirement has disappeared, but more Americans are considering alternatives to an abrupt transition from full-time employment to complete withdrawal from paid work.
Current labor data supports that broader picture: many people age 65 and older continue to work or look for work, while some retirees return to employment because of living costs, personal goals or a desire to remain active.
The three models in this guide—Work-Optional, Purpose-Driven and Intergenerational Living—should be understood as practical planning frameworks rather than official retirement categories recognized by federal agencies.
Why Redefining Retirement Looks Different in 2026
Redefining Retirement in the United States increasingly reflects a combination of longer working lives, changing household structures, healthcare costs, Social Security decisions and personal preferences about how much work or community engagement should continue.
According to the U.S. Bureau of Labor Statistics, 19.1% of people age 65 and older participated in the labor force in 2025, substantially above the 12.9% rate recorded in 2000.
These figures do not mean most older Americans want to work indefinitely, but they show that retirement is often a gradual transition rather than one universal moment when employment permanently ends.
Financial Pressure Is Part of the Shift
Some Americans remain in or return to the workforce because their Redefining Retirement savings, Social Security income and other resources do not fully support their desired standard of living.
An AARP survey released in February 2026 found that 7% of surveyed retirees had returned to the labor force during the previous six months, with making money cited far more often than simply staying active.
This financial reality means flexible retirement planning should distinguish between working by choice and working because household expenses require additional income.
Model 1: Work-Optional Redefining Retirement
A Work-Optional Redefining Retirement involves reducing dependence on full-time employment without necessarily eliminating paid work from later life altogether.
This can include part-time employment, consulting, seasonal work, freelance projects or a gradual reduction in responsibilities before fully leaving the workforce.
The model is closely related to phased retirement, an established planning concept in which workers transition from full-time employment toward retirement over a longer period.
Flexible Work Can Make the Transition More Gradual
Flexible schedules can allow older workers to remain professionally engaged while creating more time for travel, family, hobbies or other priorities that may have been difficult during a full-time career.
AARP describes phased Redefining Retirement as an arrangement that can include reduced workloads, part-time employment, flexible schedules and other gradual transitions rather than an immediate exit from work.
Availability varies considerably by employer, so workers may need to negotiate their own arrangement instead of assuming that a formal phased-retirement program exists.
- Part-time employment.
- Independent consulting.
- Seasonal work.
- Project-based assignments.
- Reduced hours before full retirement.
Additional Income Can Change Redefining Retirement Cash Flow
Even a moderate amount of earned income can reduce how much retirees need to withdraw from investment accounts during the first years after leaving full-time employment.
Working longer can also provide additional time to save, although the financial benefit depends on wages, taxes, benefits, healthcare coverage and the individual’s Redefining Retirement-account strategy.
People receiving Social Security before full retirement age should also understand that earned income above federal thresholds can temporarily reduce current benefit payments.
How Working Affects Social Security in 2026
Working while receiving Social Security Redefining Retirement benefits is allowed, but special earnings rules apply when the beneficiary has not yet reached full retirement age.
In 2026, someone under full retirement age for the entire year can earn up to $24,480 before the Social Security earnings test begins withholding benefits.
For someone reaching full retirement age during 2026, the applicable limit is $65,160 for earnings before the month full retirement age is reached, after which the earnings test no longer applies.
Working Does Not Mean Social Security Is Permanently Lost
When benefits are withheld because earnings exceed the applicable limit before full retirement age, the reduction should not automatically be interpreted as a permanent forfeiture of those benefits.
Social Security recalculates benefits after full Redefining Retirement age to provide credit for months in which payments were reduced or withheld under the earnings test.
This makes Social Security timing an important part of Work-Optional retirement planning rather than a reason to assume that retirees must choose exclusively between working and receiving benefits.
Model 2: Purpose-Driven Redefining Retirement
A Purpose-Driven Redefining Retirement places greater emphasis on meaningful activity after a primary career, which may include volunteering, mentoring, creative projects, community service or entrepreneurship.
The central idea is not that retirees must remain constantly productive, but that some individuals prefer to maintain structure and engagement through activities connected to personal values or interests.
This model can coexist with traditional leisure and does not require paid employment, making it more about how time is used than how retirement income is generated.
Community Engagement Can Use Existing Skills
Retirees may have decades of professional knowledge that can be useful to nonprofits, schools, community organizations, local businesses or younger professionals.
Mentoring, board service, teaching and volunteer work can provide opportunities to transfer that experience without recreating the demands of a full-time career.
The appropriate level of involvement depends on health, energy, family responsibilities and personal interest, so purpose-driven Redefining Retirement should remain voluntary rather than becoming another obligation.
- Mentoring younger workers or entrepreneurs.
- Serving with nonprofit organizations.
- Teaching community or adult-education classes.
- Volunteering for local causes.
Entrepreneurship Can Be Part of Redefining Retirement
Some retirees use additional flexibility to start small businesses, pursue consulting work, sell creative products or develop projects that were difficult to prioritize during their main careers.
This can provide both purpose and income, but entrepreneurship also introduces financial risk, taxes, business expenses and potentially inconsistent revenue.
Redefining Retirement funds should generally be separated carefully from speculative business capital so that an unsuccessful venture does not unnecessarily compromise long-term financial security.
Purpose Does Not Have to Generate Income
A meaningful Redefining Retirement does not require converting every hobby, creative interest or community activity into a source of revenue.
For some retirees, volunteer work, family involvement, education, travel or artistic projects may provide greater personal value precisely because they are not structured around earnings.
The financial plan should therefore support the chosen lifestyle rather than forcing every retirement activity to justify itself through measurable economic return.
Time Can Become a Retirement Asset
Redefining Retirement can create something that was scarce during working years: discretionary time that can be allocated according to personal priorities instead of employment schedules.
That time may be used for caregiving, learning, creative work, community participation or simply rest, depending on what the individual values.
Planning for retirement therefore involves deciding not only how much money is needed but also how a person wants to use the additional control over daily life.
Model 3: Intergenerational Living
Intergenerational Living describes arrangements in which multiple generations share a household or intentionally live close enough to exchange financial, practical or social support.
This can include adult children and older parents living together, grandparents sharing a home with younger family members or other multigenerational housing arrangements.
The model is not new, but current housing costs and changing family structures can make shared living more relevant when households evaluate Redefining Retirement expenses and caregiving needs.
Shared Housing Can Reduce Some Expenses
Housing is one of the largest expenses in many retirement budgets, so sharing a residence can distribute costs such as utilities, maintenance, property taxes or rent across more household members.
The U.S. Census Bureau estimated more than 5 million multigenerational households in the United States in its 2024 American Community Survey data.
That does not mean multigenerational living is primarily a Redefining Retirement strategy, but it demonstrates that shared-generation households already form a meaningful part of the American housing landscape.
- Shared housing costs.
- Shared utilities and maintenance.
- Potential caregiving support.
- Greater day-to-day social interaction.
Mutual Support Can Extend Beyond Money
Older household members may contribute childcare, household management, transportation or family knowledge, while younger residents may assist with technology, errands or physically demanding tasks.
These arrangements can provide practical support, but they work best when expectations about finances, privacy, responsibilities and caregiving are discussed before problems arise.
Intergenerational living should therefore be planned as a household arrangement with clear boundaries rather than assumed to be automatically harmonious or financially advantageous.
Housing Decisions Can Reshape Retirement Finances
A retiree’s housing strategy can significantly affect monthly expenses, access to healthcare, transportation needs and the amount of wealth tied up in property.
Intergenerational living may reduce some recurring costs, but it can also require renovations, relocation or larger housing that introduces additional expenses.
Before choosing this model, households should compare the full financial effect with alternatives such as downsizing, renting, remaining in place or moving closer without sharing one residence.
Legal and Financial Agreements May Be Useful
When family members contribute different amounts toward a home, mortgage, renovation or recurring expenses, informal assumptions can create disagreements later.
Written agreements can clarify ownership, monthly contributions, maintenance responsibilities and what happens if one member decides to move.
Estate-planning implications should also be reviewed when property ownership or substantial financial contributions are shared across generations.
Financial Planning Must Match the Retirement Lifestyle
Each Redefining Retirement model creates a different pattern of income and expenses, making lifestyle planning inseparable from financial planning.
A Work-Optional retiree may have employment income, while a Purpose-Driven retiree may rely more heavily on investments and Social Security and an intergenerational household may reduce some housing expenses.
The retirement plan should therefore model actual expected cash flows rather than applying one withdrawal strategy to every possible lifestyle.
Maintain Enough Liquid Savings
Flexible retirement models can still produce unexpected expenses, including medical bills, housing repairs, business costs or periods when part-time income disappears.
Maintaining accessible savings can reduce the need to sell investments during unfavorable market conditions or use retirement accounts for every emergency.
The appropriate reserve depends on household expenses and other income sources, but liquidity remains important regardless of which lifestyle model is chosen.
Investment Strategy Should Reflect Real Spending Needs
Investment allocations should consider the amount that needs to be withdrawn, the expected length of Redefining Retirement and the retiree’s ability to tolerate market fluctuations.
Someone continuing to earn meaningful income may initially depend less on portfolio withdrawals than someone who leaves paid employment completely.
That difference can influence asset allocation and withdrawal planning, but investment decisions should still reflect long-term objectives rather than short-term lifestyle labels alone.
Healthcare Remains Central to Every Retirement Model
Flexible work, volunteering or multigenerational living do not eliminate the need to plan carefully for healthcare expenses during retirement.
Medicare eligibility, supplemental coverage, prescription costs and out-of-pocket expenses can materially affect the amount a household needs each year.
Anyone planning to leave employer coverage before becoming Medicare-eligible should also understand how health insurance will be maintained during the transition period.
Family Support Is Not a Substitute for Long-Term Care Planning
Intergenerational households may provide informal help with daily activities, but families should not automatically assume relatives will be able to provide intensive long-term care.
Caregiving can require substantial time, specialized skills and physical effort, creating costs for both the person receiving care and the family member providing it.
Redefining Retirement planning should therefore examine long-term care needs separately from normal household support and consider how potential expenses would be funded.
Social Security Remains a Foundation for Many Retirees
Social Security continues to provide a significant source of retirement income for millions of Americans, regardless of which lifestyle model they choose.
For 2026, Social Security benefits received a 2.8% cost-of-living adjustment, and the estimated average monthly benefit for retired workers increased to approximately $2,071 in January.
The actual benefit varies significantly by earnings record and claiming age, so national averages should not be used as a substitute for reviewing an individual’s Social Security estimate.
Claiming Age Can Affect Long-Term Income
Redefining Retirement benefits can generally begin as early as age 62, but claiming before full retirement age reduces the monthly amount compared with waiting.
Delaying benefits beyond full retirement age can increase monthly payments until age 70, creating another variable to consider when employment income or other assets can support a later claim.
The most appropriate strategy depends on longevity expectations, household circumstances, survivor considerations, health and the availability of other retirement resources.
Retirement Planning Must Consider Social Security’s Long-Term Outlook
The 2026 Social Security Trustees Report continues to show a long-term financing challenge for the program even though scheduled benefits are currently being paid in full.
Under the trustees’ intermediate projections, the Old-Age and Survivors Insurance Trust Fund can pay full scheduled benefits until the fourth quarter of 2032.
If Congress made no changes after reserve depletion, continuing program income would be sufficient to pay approximately 78% of scheduled OASI benefits under that projection.
Projected Shortfalls Are Not the Same as Social Security Disappearing
The projected depletion date refers to trust-fund reserves and does not mean the Social Security program would suddenly have no revenue.
Payroll taxes and other continuing income would still finance a substantial portion of benefits even under a scenario in which lawmakers enacted no corrective legislation.
Redefining Retirement plans should therefore acknowledge the financing challenge without assuming either that every promised benefit is guaranteed unchanged or that Social Security will vanish entirely.
How These Models Affect Communities and Employers
More flexible transitions into retirement can affect employers by increasing demand for part-time roles, consulting arrangements, phased-retirement programs and knowledge-transfer opportunities.
Communities may also experience greater participation from older adults through volunteering, entrepreneurship, caregiving and local organizations.
These effects can be positive, but they should not be overstated because many retirees may still prefer traditional retirement centered primarily on leisure and family life.
Older Workers Continue to Contribute to the Economy
With nearly one in five Americans age 65 and older participating in the labor force in 2025, older workers remain a meaningful part of the U.S. employment landscape.
Their continued employment may preserve experience and institutional knowledge, but organizations also need policies that address flexibility, accessibility and age discrimination.
The economic impact of later-life work therefore depends on whether employment arrangements remain genuinely beneficial to both workers and employers.
Housing Design May Need to Serve More Generations
Multigenerational households can increase demand for homes that balance shared living spaces with privacy and accessibility for people at different stages of life.
Features such as ground-floor bedrooms, accessible bathrooms or separate living areas can make shared arrangements more practical as household members age.
Communities with transportation, healthcare and everyday services nearby may also be better suited to older residents who want to remain socially connected without depending entirely on driving.
Choosing the Right Retirement Model
These three frameworks should not be treated as mutually exclusive choices because one person may combine elements of all three at different stages of Redefining Retirement.
Someone might work part-time during their sixties, transition toward volunteer or creative projects later and eventually move into a multigenerational household as family needs change.
The most useful model is therefore the one that fits current finances, health, relationships and priorities while remaining adaptable to future changes.
Questions to Ask Before Changing Your Retirement Plan
Start by determining how much dependable income the household will have from Social Security, pensions, employment and other predictable sources.
Then compare expected spending, healthcare costs, housing arrangements and investment withdrawals under several possible Redefining Retirement lifestyles.
Finally, consider whether the chosen arrangement remains workable if employment ends, health changes, family support becomes unavailable or expenses rise unexpectedly.
- How much predictable income will I have?
- Do I want or need to continue working?
- How important is community or volunteer involvement?
- Would shared housing improve my finances or quality of life?
- How will healthcare and long-term care be funded?
- How much liquid savings will remain available?
| Retirement Framework | Key Consideration |
|---|---|
| Work-Optional | Combines reduced employment with greater schedule flexibility and potential additional income. |
| Purpose-Driven | Focuses on volunteering, mentoring, entrepreneurship, creative projects or other meaningful activities. |
| Intergenerational Living | Can combine shared housing costs, family support and greater day-to-day social interaction. |
| Planning Approach | These are flexible lifestyle frameworks rather than official retirement categories and can overlap over time. |
Frequently Asked Questions About New Redefining Retirement Models
No. They are practical lifestyle frameworks used to describe different ways people may structure retirement. Federal agencies do not classify retirement into these three official categories.
Older Americans remain significantly more active in the labor force than several decades ago. BLS data shows 19.1% of people age 65 and older participated in the labor force in 2025, compared with 12.9% in 2000.
Yes. However, if you are younger than full retirement age, earnings above applicable 2026 limits can temporarily reduce current benefit payments. Beginning with the month you reach full retirement age, the earnings test no longer applies.
It can reduce some housing and household costs when expenses are shared, but results depend on the property, ownership structure, family arrangement and responsibilities of each household member.
No. A retirement lifestyle can evolve over time, combining part-time work, volunteer activity, entrepreneurship, travel, independent living and multigenerational housing at different stages.
What Redefining Retirement Means in 2026
Redefining Retirement in 2026 is less about replacing traditional retirement and more about recognizing that Americans have a wider range of ways to organize work, income, housing and personal purpose after their main careers.
Current labor-force data, the continued importance of Social Security and the presence of millions of multigenerational households show why retirement planning increasingly needs to reflect actual household circumstances instead of one idealized lifestyle.
The strongest retirement plan is one that remains financially sustainable while giving individuals enough flexibility to adjust work, housing and daily activities as their health, relationships and priorities change.